France Is Borrowing at Increasingly Higher Costs
The clearest sign of growing concerns is the performance of French government bonds. The yield on 10-year French bonds rose by approximately 0.7 percentage points in September, reaching its highest level since 2002. In early October, it even briefly exceeded 5%.* A higher yield means that investors are demanding a higher return for lending their money to France. The spread between French and German bonds is also significant. Germany is considered one of the most reliable borrowers on the European market, which is why its bonds serve as an important benchmark. The spread between the yields on 10-year French and German bonds approached 1.6 percentage points in early October. This was the highest level since the European debt crisis in 2011. This is also important for France because it plans to issue medium- and long-term government bonds in 2027 in a record volume of 340 billion euros. The longer yields remain high, the more expensive it will be to finance new debt and refinance older debt.
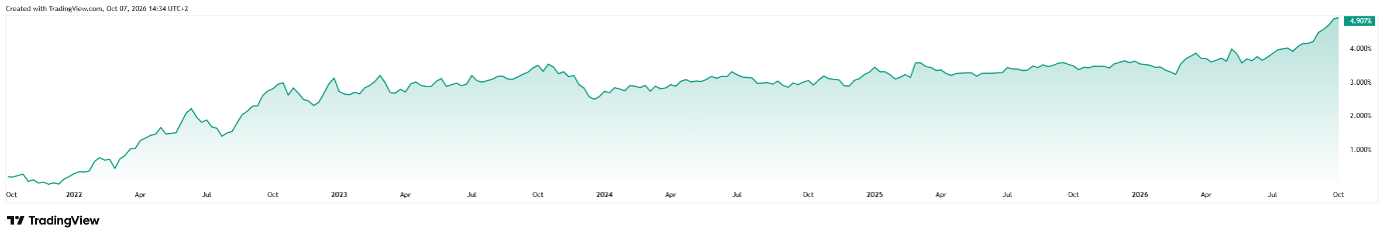
Performance of French 10-year bond yields over the past 5 years.*
The government wants to reduce the deficit, but debt is still expected to grow
The French government expects the public deficit to reach approximately 5.4% of GDP in 2026. In its 2027 budget proposal, it aims to reduce it to 5% of GDP through measures to restore public finances totaling 54 billion euros. Even so, France will still be far from the 3% of GDP threshold set by European Union rules. At the same time, interest costs are rising. In 2026, the country is expected to pay approximately 79.2 billion euros in debt service, and in 2027, that figure will rise to 91.2 billion euros. In just one year, the amount allocated solely to interest payments is set to increase by 12 billion euros. Furthermore, the French Ministry of Finance expects public debt to continue rising despite planned austerity measures. From approximately 119.3% of GDP in 2026, it is projected to rise to 121.7% of GDP in 2027. The reason is that the deficit will remain too high for the overall debt-to-GDP ratio to begin declining. The government therefore needs to convince investors not only that it can pass the 2027 budget, but also that it can actually implement the planned savings. [1]
Concerns over France are already weighing on the euro
Tensions in the French bond market have also begun to affect the common European currency. On October 5, the euro fell to about $1.116, its weakest level since May 2025.* Over the course of four weeks, it lost approximately 3.1% against the dollar. One of the reasons was precisely investors’ concerns about French debt and the government’s ability to bring the deficit under control. When investors view the situation in a major eurozone economy as riskier, demand for euro-denominated assets may also decline. At the same time, the euro was weakened by high U.S. interest rates and persistent inflation in the U.S., which supported the dollar. France is therefore not the sole reason for the euro’s decline, but its budget problems have become a significant factor in the foreign exchange market. This development is also important for businesses and investors in the eurozone, as a weaker euro makes imports of goods and raw materials paid for in dollars more expensive and may increase costs for European companies.
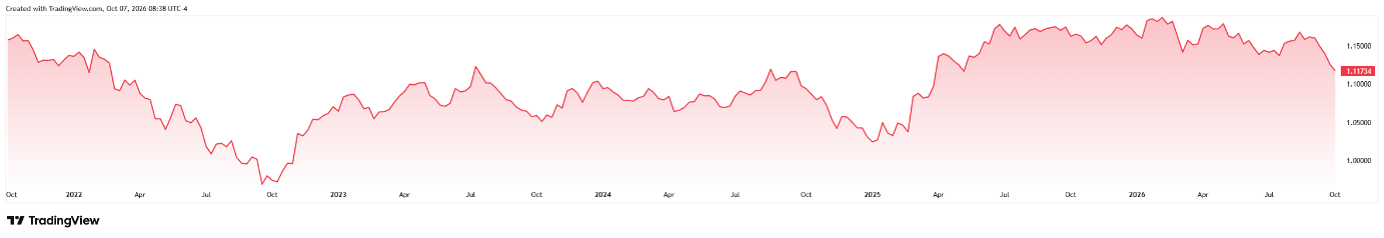
The euro’s exchange rate against the dollar over the past 5 years.*
The ECB can intervene only under certain conditions
The European Central Bank has a tool that allows it, in exceptional cases, to purchase government bonds of a country whose borrowing costs are rising sharply without sufficient economic justification. This mechanism was established in 2022 to prevent market turmoil from disrupting the functioning of monetary policy in the eurozone. However, this does not mean that the ECB can simply start buying French bonds just because their yields are rising. In making its decision, it assesses the state of the country’s public finances, the sustainability of its debt, compliance with European budget rules, and the cause of the rise in financing costs. On October 7, Emmanuel Moulin, president of the Bank of France, stated that France does not currently need assistance from the ECB and that a solution must come primarily through domestic fiscal policy. Therefore, the key to future developments will be whether the government can reduce the deficit, pass the 2027 budget, and maintain investor confidence. If yields on French bonds continue to rise and the problems begin to spread more significantly to other eurozone countries, the question of potential ECB intervention may take on greater significance. [2]
* Past performance is no guarantee of future results.
[1,2] Forward-looking statements are based on assumptions and current expectations, which may be inaccurate, or on the current economic environment, which is subject to change. Such statements are not guarantees of future performance. They involve risks and other uncertainties that are difficult to predict. Actual results may differ materially from those expressed or implied in any forward-looking statements.
Sources:
https://www.reuters.com/business/us-30-year-bond-yield-hits-fresh-24-year-high-2026-10-07/
https://finance.yahoo.com/economy/policy/articles/france-bond-rout-starts-dragging-184315755.html